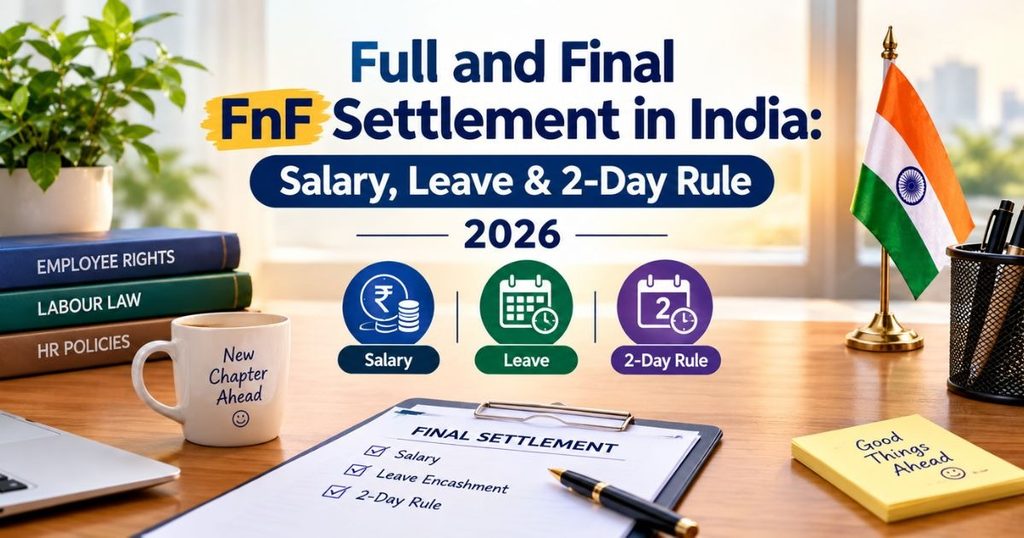
Full and Final FnF Settlement in India is the process used to calculate and pay the amounts due to an employee when employment ends because of resignation, termination, retirement, or another form of separation. It can include unpaid salary, leave encashment, deductions, reimbursements, incentives, gratuity, and other applicable dues.
Understanding Full and Final FnF Settlement in India is especially important in 2026 because employees and employers need to distinguish between wages payable after separation, company-policy items, statutory benefits, and deductions. The applicable payment timeline can also depend on the nature of the payment and the law governing the employment relationship.
What Full and Final FnF Settlement Means
Full and final settlement, commonly called FnF, is the financial closing process between an employee and employer after employment ends. The calculation normally considers salary earned up to the last working date, eligible leave, reimbursements, incentives, deductions, and applicable statutory benefits.
🌞 Full and final settlement brings an employee’s outstanding financial items together after leaving a company. It may include salary, leave encashment, reimbursements, incentives, and approved deductions. 📋
💼 An employee settlement is more than a final salary payment because several payroll components may need review. HR and payroll generally reconcile records before preparing the final amount.
✨ FnF settlement helps close the financial side of an employment relationship. A properly prepared settlement should clearly show earnings, deductions, benefits, and the amount finally payable.
🧾 A final salary settlement usually starts with the employee’s last working date. Payroll then determines how much salary was earned and what additional amounts or deductions apply.
🔍 Understanding FnF calculation makes the process easier to verify. Employees can compare the settlement statement with their payslips, leave balance, reimbursement records, and employment terms.
🏢 Companies use the FnF process to complete employee exit settlement formally. HR, payroll, finance, and sometimes other departments may contribute information before payment is released.
💰 The full and final settlement amount can differ significantly between employees. Differences may arise from salary structure, unused leave, notice obligations, incentives, deductions, and statutory benefits.
📅 Settlement timing is an important part of the exit process. Employees should check the applicable law, employment terms, and company procedure rather than assuming every component follows one identical timeline.
🤝 A transparent settlement can reduce confusion when employment ends. Providing a clear breakdown allows both sides to identify calculation errors and resolve questions before the employment records are closed.
📑 The settlement letter is useful evidence of the financial closure of employment. Employees should keep it with the final payslip, payment confirmation, and other important employment documents.
🌿 Resignation settlement commonly involves salary through the last working date and any applicable adjustments. Notice period recovery, leave encashment, reimbursements, and other contractual items may also need consideration.
🛡️ Termination settlement can involve different circumstances from resignation. The final calculation should therefore reflect the reason for separation and any statutory or contractual obligations that apply.
🎓 Retirement settlement may include salary, leave-related payments, gratuity where eligible, and other benefits. The exact components depend on applicable law, employment terms, and the employee’s circumstances.
🧮 FnF calculation should be based on reliable payroll records rather than estimates. Attendance, salary structure, leave balances, deductions, and approved claims can all affect the final figure.
💡 An employee should not assume that gross monthly salary equals the final settlement. The actual payment may include additional earnings while also accounting for taxes, advances, recoveries, or other permitted deductions.
📬 A settlement statement gives employees a practical way to understand how the final payment was reached. If an item appears incorrect, the employee can ask HR or payroll for clarification.
🔐 Employee clearance often forms part of the FnF process. Company assets, outstanding advances, access-related matters, and departmental approvals may need to be completed before internal closure.
📊 Payroll settlement requires accurate data from several sources. Attendance records, leave records, salary information, reimbursement claims, and approved deductions can all influence the final calculation.
🌸 A well-documented exit process protects both sides from unnecessary disputes. Keeping copies of settlement documents provides a useful record if questions arise later.
🕊️ FnF is essentially the financial closing stage of employment. When the calculation is transparent and supported by records, employees can better understand what they have received and what remains outstanding.
Salary Included in an FnF Settlement
Salary earned up to the last working date is one of the most common components of an FnF payment. Payroll generally calculates the payable amount according to the employee’s salary structure, attendance, working days, applicable deductions, and payroll cycle.
💵 Unpaid salary may form the central part of a final settlement when an employee leaves before the normal payroll date. Payroll calculates the earned amount for the relevant period before applying permitted deductions.
📅 The last working date is important because it establishes the period for which salary is normally calculated. Accurate attendance and employment records help payroll determine the amount earned through separation.
🧾 A final payslip can help employees understand their final salary calculation. It may show earnings, deductions, taxes, and the resulting net amount transferred to the employee.
🔢 Salary calculations can become complicated when an employee leaves partway through a month. The applicable payroll method and employment terms determine how the partial-month salary is calculated.
💼 Basic salary and other salary components may be treated differently for specific statutory or contractual calculations. Employees should review their salary structure rather than assuming every component is calculated identically.
📌 Pending salary means money already earned but not yet paid through the normal payroll process. Such amounts should be checked carefully against attendance and payroll records.
🧮 Payroll teams may review working days, unpaid leave, attendance corrections, and approved adjustments before finalizing salary. These records can change the amount shown in the settlement statement.
💳 Salary deductions may include amounts that are legally permitted or contractually applicable. Examples can include certain recoveries, taxes, advances, or notice-related adjustments.
🏦 The final salary settlement is normally transferred through the employer’s established payment process. Employees should retain bank transaction records as evidence of payment.
📄 Employees should compare the final payslip with their previous salary slips. This can make it easier to identify unusual deductions or missing salary components.
🔎 If salary appears lower than expected, the employee can request a written calculation from payroll. A clear calculation helps identify whether the difference relates to deductions, attendance, tax, or another adjustment.
🌟 Incentives may require separate verification because eligibility can depend on company policy, performance conditions, or the incentive period. They should not automatically be assumed to be payable in every exit.
💡 Allowances can also affect the final payroll calculation. Whether an allowance is payable for the final period depends on the salary structure and applicable employment terms.
🧷 Tax deductions can reduce the net amount even when the gross settlement appears correct. Income tax and TDS treatment should be checked against the employee’s applicable tax position.
📚 Payroll records are important supporting evidence during settlement. Employees should preserve salary slips, appointment documents, tax records, and relevant correspondence for future reference.
🤝 When both employee and payroll team use the same records, settlement discussions are usually easier. Questions can be addressed by checking dates, figures, and documented policies.
🛠️ Salary advances may be adjusted against the final amount when an outstanding balance exists and the deduction is applicable. The settlement statement should make such adjustments visible.
⏰ A delayed salary component should not simply be assumed to be lost. Employees can ask payroll to identify whether the amount was omitted, held for verification, or included under another settlement component.
📋 A good FnF statement separates earnings from deductions. This makes the calculation easier to understand and gives the employee a practical record of the financial closure.
🌱 Reviewing the salary portion carefully can prevent small errors from becoming larger disputes. Employees should verify dates, earnings, deductions, taxes, and the final net payment before closing their records.
Leave Encashment and Unused Leave
Leave encashment is another common FnF component, but eligibility and calculation can depend on the type of leave, applicable law, company policy, and employment terms. Employees should check their leave balance and the rules governing unused leave.
🌿 Leave encashment converts eligible unused leave into a monetary payment when employment ends. The calculation depends on the applicable leave category, policy, and legal requirements.
📅 Leave balance should be checked before the final settlement is prepared. Attendance and leave-management records normally provide the information needed to determine unused eligible leave.
💰 Not every type of leave is automatically encashed in every organization. Employees should review their employment policy and applicable law to determine which leave qualifies.
🧾 The settlement statement should identify any leave-related payment separately where applicable. A separate line can make the calculation easier to verify and understand.
🔍 Earned leave may be treated differently from casual or other leave categories. The applicable policy and statutory framework determine whether unused days can be converted into payment.
🏢 Company leave policies can establish practical procedures for calculating unused leave. Employees should compare the policy with their recorded leave balance before accepting the final calculation.
📊 Accurate leave records are essential for FnF calculation. Even a small difference in the recorded balance can affect the final amount paid to the employee.
✨ Employees who believe their leave balance is incorrect should raise the issue promptly with HR. Supporting records such as approved leave applications can help clarify the discrepancy.
🧮 Leave encashment calculations may use a specified salary component rather than the entire monthly package. The applicable rule or company policy should be checked before estimating the amount.
📌 A final settlement can include both salary and eligible leave encashment. These should be treated as separate calculation items so the employee can understand each amount.
🗂️ Leave applications, approvals, and attendance records can support the final leave calculation. Keeping copies is useful when the employee wants to verify the settlement later.
🌸 Unused leave does not necessarily mean automatic cash payment in every situation. The actual entitlement depends on the relevant leave rules and the employee’s terms of service.
💼 Employees should not calculate leave encashment only from their gross salary unless the applicable formula specifically requires it. Different policies may use different salary bases.
🔐 HR clearance and leave reconciliation may occur before final payroll processing. This allows the company to confirm the employee’s final leave position before preparing the settlement.
📖 Understanding leave rules before resignation can help employees anticipate the settlement. The employee handbook or HR policy may explain carry-forward and encashment provisions.
🧾 A missing leave payment can be questioned using documented records. Employees should provide the relevant leave balance or approved applications when asking payroll to review the calculation.
💡 Leave encashment can become especially important when an employee has accumulated eligible leave over several years. The applicable statutory and organizational limits should be checked carefully.
🤝 A clear leave reconciliation benefits both employee and employer. It reduces uncertainty by establishing the exact recorded balance and the rule used to calculate payment.
📬 Employees should retain the final leave statement if one is provided. It can help explain how the unused leave figure was determined.
🌟 Reviewing leave before the final payroll run can make the FnF process smoother. Employees can confirm their balance, eligibility, calculation method, and payment before the employment file is closed.
Understanding the 2-Day Rule in 2026

The often-discussed “2-day rule” relates to the statutory timing for payment of wages after certain forms of employment separation under India’s labour-law framework. It is important to distinguish the statutory wage-payment requirement from every other component that may appear in an FnF settlement.
⏱️ The two-day provision is associated with wages payable after specified employment separations under the applicable labour-law framework. It should not automatically be interpreted as a universal two-day deadline for every FnF component.
📚 Employees should distinguish “wages” from other settlement items. Statutory benefits, reimbursements, documentation, and certain contractual payments may follow different rules or processes.
🧾 The reason for separation can matter when applying a payment-timing rule. Resignation, dismissal, discharge, and retrenchment should be considered according to the wording of the applicable legislation.
🔎 The phrase “2-day rule” is often used broadly in online discussions. Employees should look at the actual legal provision and its applicability instead of relying only on a simplified summary.
🏢 Employers may have internal payroll procedures that involve additional steps. Those procedures do not necessarily replace statutory obligations that apply to the relevant payment.
📅 The meaning of “two days” should be read according to the applicable legal provision rather than assumed to mean two calendar days in every circumstance. The exact wording matters.
💼 Employees leaving a company should ask payroll which parts of the settlement are treated as wages and which are separate benefits or adjustments. This distinction can clarify expected payment timing.
⚖️ Labour-law compliance can depend on the facts of employment. The applicable legislation, employment category, wage definition, and circumstances of separation should be considered together.
📌 A two-day wage-payment requirement should not be confused with a general promise that every document will be completed within two days. Payment and administrative closure can involve different processes.
🧮 An employee may receive wages promptly while another settlement item requires additional verification. Reimbursements, incentives, or disputed amounts may involve separate calculations.
🛡️ Keeping written records of the last working date and separation communication can be useful. These records establish important dates when an employee follows up about settlement timing.
📩 If payment does not arrive when legally required, an employee can first request a written status update from HR or payroll. The communication should clearly identify the outstanding amount and relevant date.
🗃️ Employees should preserve resignation acceptance, termination communication, payslips, and settlement correspondence. These documents provide a useful record if a payment-timing question later arises.
🌐 India’s labour-law framework has undergone significant changes, making it important to check the rules applicable in 2026. Older articles may describe earlier provisions or timelines that no longer reflect the current framework.
🧠 The 2-day rule should therefore be understood carefully rather than used as a blanket statement. The legal requirement may apply specifically to wages while other settlement components require separate treatment.
💬 If an employer communicates a different timeline, employees can ask which component is pending and why. A written explanation is more useful than relying on informal statements.
📋 Payroll teams can reduce confusion by separating salary from other FnF items. Clear descriptions help employees understand which amounts have been paid and which remain under review.
⚠️ A disputed amount should be identified separately from an undisputed amount. This makes it easier to determine what has already been calculated and what still requires clarification.
🤝 Employees and employers benefit from using the exact statutory language when discussing payment deadlines. Precise wording prevents the common mistake of treating every FnF item as identical.
🌟 Anyone dealing with a 2026 settlement should verify the current applicable law and employment circumstances. This is particularly important when relying on the “2-day rule” for a specific payment.
Notice Period, Recovery, and Buyout
Notice period adjustments can significantly change the final settlement. Depending on the employment terms and circumstances, an employee may serve the required notice, receive an approved waiver, or have a notice-related recovery or buyout amount considered.
📅 The notice period is the period an employee may be required to work after resignation under the applicable employment terms. Its treatment can directly affect the final settlement.
💼 Notice period recovery may reduce the amount payable when an employee leaves without completing an applicable notice obligation. The exact calculation should follow the relevant contract and policy.
💰 Notice period buyout generally refers to payment made instead of serving some or all of the required notice. The contractual terms should explain whether such an arrangement is permitted.
🧾 Employees should check the appointment letter before accepting a notice-related deduction. The document may specify notice length, recovery provisions, and circumstances in which a waiver can occur.
🔍 A notice recovery should be clearly shown in the settlement statement. Employees should be able to identify the amount, calculation basis, and reason for the deduction.
🤝 Employers sometimes approve early release by agreement. When that happens, employees should keep written confirmation because it can affect the final notice-period calculation.
📌 Notice-related deductions should not be confused with statutory tax deductions. They arise from employment terms or applicable rules and should appear separately in a transparent settlement.
🛠️ If an employee has served part of the notice, the outstanding period may be relevant to the calculation. The actual treatment depends on the applicable agreement and circumstances.
📚 Company policy may provide procedures for notice waiver or buyout. Employees should check those procedures before making assumptions about their final payment.
📊 The notice-period amount can materially affect the FnF amount. Reviewing the calculation early helps employees understand why their expected payment differs from their normal monthly salary.
🧮 Payroll should use the appropriate salary basis specified by the applicable employment terms when calculating notice-related recovery. Employees can request the formula if the figure is unclear.
📬 Written communication about early release is especially useful. An approved waiver can provide evidence of the agreed last working date and notice treatment.
🌱 Employees should not rely only on verbal assurances about notice recovery. Keeping emails or official HR communications creates a clearer record for the final settlement.
🔐 Exit clearance can also influence when payroll receives the information needed to finalize a settlement. Employees should complete required handovers and return company assets promptly.
💡 Notice-period rules can differ between organizations and employment arrangements. A calculation from one employer should not automatically be applied to another employer.
🧾 A settlement letter should ideally identify significant notice adjustments. This gives the employee a practical explanation of how the final amount was reached.
⚖️ If a notice deduction appears inconsistent with the employment agreement or applicable law, the employee can request clarification and supporting calculations from HR or payroll.
🗂️ The appointment letter, resignation email, acceptance letter, and last-working-date confirmation can collectively establish the relevant notice facts. Keeping them together makes review easier.
🕊️ Clear notice-period communication can prevent disputes during employee exit. Both sides benefit when the expected notice treatment is agreed before the final payroll calculation.
🌟 Reviewing notice provisions before resignation gives employees a better understanding of possible settlement adjustments. It also helps them plan financially for the transition between jobs.
Provident Fund, Gratuity, and Statutory Benefits
Statutory benefits may form an important part of an employee’s separation process, but they do not necessarily operate exactly like ordinary salary. Provident Fund, gratuity, and other benefits can have separate eligibility, calculation, processing, and payment requirements.
🏦 Provident Fund is generally administered through the applicable EPFO framework rather than simply being treated as ordinary monthly salary. Employees should follow the relevant PF process for their account and circumstances.
📋 PF contribution records can help employees verify whether contributions were credited correctly. The employee and employer portions may appear separately in applicable records.
💼 Employer PF contribution is not normally the same as cash salary received by the employee. Its treatment follows the statutory social-security framework and applicable employment arrangements.
🎓 Gratuity is a statutory benefit subject to eligibility and applicable law. Employees should not assume that every employee leaving a company automatically receives gratuity.
🧮 Gratuity calculation depends on the applicable legal formula and qualifying service. The exact amount should be calculated using the rules that apply to the employee’s circumstances.
🔎 Gratuity eligibility can depend on factors such as length of service and the reason for separation. Employees should verify the applicable statutory requirements rather than relying on general online calculators.
📑 PF and gratuity may involve processes separate from the employer’s ordinary final salary payroll. Therefore, a completed salary settlement does not necessarily mean every statutory benefit has been transferred immediately.
🛡️ Employees should keep their UAN, service records, salary documents, and relevant employment information accessible. These details can help with later verification of statutory benefits.
🌱 Statutory benefits are governed by specific legal frameworks, which can change over time. For a 2026 settlement, employees should use current official rules when determining eligibility.
💡 A final settlement statement may mention statutory deductions or benefits without itself completing every external claim process. Employees should distinguish payroll entries from separate benefit procedures.
📬 Employers can provide information about statutory benefit processing as part of the exit process. Employees should request clarification if they are unsure whether an item is included or handled separately.
🧾 A PF contribution appearing on a payslip does not necessarily mean the final withdrawal or transfer is completed. Account-level processing follows the applicable statutory mechanism.
⚖️ Gratuity disputes should be assessed against the governing legal provisions rather than only company policy. Statutory rights can have requirements that differ from internal procedures.
📊 Employees should compare statutory contribution records with salary slips when checking their employment records. Differences can then be raised with the relevant employer or statutory authority.
🏢 HR departments often coordinate information for statutory benefits, while payroll may handle salary-related calculations. Understanding these separate roles can make the exit process easier to follow.
🔐 Maintaining employment records after resignation is important because statutory benefits may be relevant long after the final salary is received. Digital copies are convenient for long-term storage.
🌟 Employees should avoid treating every amount mentioned in an FnF statement as immediately withdrawable cash. Some amounts may represent statutory contributions or benefits requiring another process.
📚 Current legal guidance is particularly important for gratuity and social-security questions. Rules can differ according to the applicable law and the employee’s employment situation.
🤝 A clear separation checklist can help employees track salary, PF, gratuity, tax documents, and other benefits independently. This reduces the chance of overlooking an item during the transition.
🕊️ Statutory benefits are an important part of employment records, but each has its own rules. Reviewing them separately from ordinary payroll can make the overall settlement easier to understand.
Deductions, Tax, TDS, and Reimbursements
The final settlement may contain several deductions and adjustments. These can include income-tax deductions, TDS, advances, notice-related recovery, approved claims, or other applicable items. Reimbursements may also need separate verification.
💳 Salary deductions can reduce the gross settlement amount before the final net payment is calculated. Each significant deduction should be identifiable in the settlement statement.
🧾 TDS may apply to taxable payments according to the applicable tax rules. Employees should review their tax documents and ensure that reported deductions correspond with the payments received.
💰 Taxable salary is not always identical to the total settlement amount. Different components can receive different tax treatment depending on the applicable provisions.
🔍 Income tax calculations can become more complicated when salary, incentives, leave-related payments, and other amounts are paid together. Employees should review the tax treatment of significant components.
📋 Reimbursement claims may need supporting bills and approval before they can be included in the final payment. Missing documentation can delay processing of an otherwise valid claim.
🏢 Employees should submit outstanding reimbursement documents before leaving where possible. This gives the finance team enough information to verify and process eligible expenses.
🧮 An advance received from the employer may be adjusted against the final settlement if an amount remains outstanding. The settlement statement should clearly identify the adjustment.
📌 Tax deductions should be distinguished from company recoveries. They arise for different reasons and should not be combined into one unexplained figure.
💼 Incentives may have specific eligibility conditions. An employee should check the relevant plan or policy to understand whether an incentive remains payable after separation.
📊 Allowances can have different tax and payroll treatment depending on their nature. Employees should avoid assuming that every allowance is automatically taxable or tax-free.
📬 If TDS appears unexpectedly high or low, employees can request the payroll team’s calculation and review their tax records. The appropriate tax treatment may depend on the full-year position.
🧾 A final payslip is useful for reconciling gross earnings, deductions, and net payment. Employees should store it with their other tax and employment records.
🔎 Employees can request clarification for any unfamiliar deduction. A clear explanation should identify what the deduction represents and the basis on which it was applied.
🌿 Reimbursements are generally different from salary because they relate to eligible business expenses. Their treatment depends on the applicable company process and tax rules.
⚖️ Tax treatment can change depending on the type of payment and current legislation. For important tax questions, employees should use current official guidance or qualified tax advice.
💡 The net FnF amount can therefore look much smaller than the combined gross components. This does not necessarily indicate an error; deductions and tax treatment may explain the difference.
🗂️ Supporting documents make settlement verification easier. Employees should retain reimbursement approvals, salary slips, tax statements, and relevant payroll communications.
🛡️ A transparent deduction list helps prevent confusion. Employees should be able to distinguish taxes, recoveries, adjustments, and other deductions from their underlying earnings.
🤝 Payroll and finance teams can often resolve discrepancies by checking the source records. Providing specific dates and documents usually makes an inquiry more productive.
🌟 Understanding the difference between gross settlement and net payment helps employees plan their finances after leaving a job. The final bank credit should be compared with the settlement statement.
FnF Settlement Process and Required Documents

A structured FnF process normally involves employee separation, clearance, payroll calculation, review, approval, payment, and documentation. The exact workflow varies by organization, but maintaining complete records is useful throughout the process.
📝 The FnF process generally begins when the employee’s separation is formally recorded. HR confirms the relevant dates and communicates the information needed by payroll and other departments.
📅 The last working date is one of the most important details in the process. It affects salary calculation, leave reconciliation, and several other employment records.
🏢 HR clearance may involve confirming resignation, handover, company policy requirements, and employment records. Completion of these steps can help payroll receive accurate exit information.
💻 Asset clearance confirms whether company property has been returned. Laptops, identification cards, equipment, documents, or other assets may need to be recorded before closure.
💰 Finance clearance can involve advances, expense claims, reimbursements, or other financial items. These records may affect the final settlement calculation.
📊 Payroll reviews salary, attendance, leave, deductions, and other applicable components. The information is then used to prepare the employee settlement.
🧾 A settlement letter or statement provides a written record of the calculation. Employees should check that major earnings and deductions are represented accurately.
📑 Employment records can include appointment letters, salary slips, leave statements, tax documents, and separation correspondence. Keeping these records can be valuable after employment ends.
🔍 Employees should compare the settlement documents with their own records. Differences are easier to resolve when the employee can identify the exact component in question.
📬 The final settlement payment should be supported by a payment record. A bank statement or transaction confirmation can help establish when the amount was actually received.
🗂️ Companies may use an internal FnF settlement format to organize information consistently. The format can differ between employers while covering similar payroll components.
🛡️ A well-maintained document trail benefits both parties. It provides evidence of calculations, approvals, communications, and payments if a question arises later.
✨ Employees should request missing documents rather than relying only on verbal confirmation. Written records are easier to store and review when changing jobs.
🔐 Exit process requirements may involve several departments, so settlement should not be viewed as a payroll-only activity. HR, finance, IT, and management can have separate clearance responsibilities.
🧮 The settlement calculation should be traceable to underlying records. An employee should be able to understand how the final figure was produced.
📋 A useful document checklist can include the settlement statement, final payslip, tax documents, PF information, reimbursement status, and separation communication.
💡 Employees should save important documents before losing access to company systems. Work email and employee portals may no longer be accessible after separation.
🌸 A complete settlement file makes future employment and tax administration easier. It also provides useful evidence if an employment record needs to be checked years later.
🤝 Prompt communication between HR, payroll, finance, and the departing employee can reduce avoidable delays. Clear ownership of each step makes the process more predictable.
🌟 The goal of settlement documentation is clarity. When each payment, deduction, approval, and record is properly documented, the employee can close the employment relationship with a clear financial record.
How Employees Can Check Their Final Settlement
Employees should independently review their FnF calculation rather than relying only on the final bank credit. A practical review includes the last working date, salary, leave balance, notice adjustment, reimbursements, statutory benefits, deductions, and tax information.
🔍 Start by checking the last working date shown in the settlement. An incorrect date can affect salary, leave, and other calculations.
🧾 Compare the final payslip with the previous salary slip. This can reveal whether the expected salary components and deductions have been carried forward correctly.
📅 Review the recorded leave balance before accepting the leave encashment figure. Check approved leave records if the balance appears different from your own records.
💰 Compare the gross settlement amount with each individual component. Adding the listed earnings can help confirm whether the total has been calculated correctly.
📉 Review every deduction separately rather than checking only the final net amount. This makes unexplained recoveries easier to identify.
🧮 Check any notice period recovery against the appointment letter and separation communication. The amount should be understandable from the applicable terms.
🧾 Review reimbursement claims that were submitted before departure. Confirm which claims were approved, rejected, paid, or still pending.
🏦 Check the actual bank credit against the net amount shown in the settlement statement. Keep the payment confirmation for your records.
📊 Review tax and TDS information carefully. The settlement’s tax treatment may affect the net payment and later tax filing.
📚 Check statutory benefit records separately. PF and gratuity may involve processes that are not identical to ordinary salary payment.
🗂️ Keep the settlement letter, final payslip, payment proof, and separation documents together. A single organized folder can make future verification much easier.
💬 If you find an inconsistency, contact HR or payroll with a specific question. For example, identify the missing amount, relevant date, and supporting document.
📌 Avoid making a general complaint when a detailed calculation question can resolve the issue faster. Specific figures make it easier for payroll to investigate.
🛠️ Ask for the calculation sheet if the final amount is difficult to understand. A component-by-component breakdown can reveal the reason for differences.
🌱 Keep copies of important employment records even after the settlement is completed. Some documents may be useful for tax, statutory benefits, or future verification.
⚖️ If a significant legal issue remains unresolved, employees can consider obtaining professional advice based on their specific employment circumstances. General online information may not cover every case.
🤝 Give HR an opportunity to correct genuine administrative errors. Payroll mistakes can sometimes be resolved quickly when the relevant supporting records are provided.
🔐 Protect personal salary and tax documents after leaving the company. Store them securely because they contain sensitive employment and financial information.
✨ A careful review does not need to be complicated. Checking dates, earnings, leave, deductions, benefits, taxes, and payment proof covers most common settlement questions.
🌟 Completing this review gives employees a clear record of their financial exit. It also helps identify unresolved items before the employment relationship is fully closed.
Common FnF Settlement Questions, Delays, and Be. st Practices

Settlement questions often arise because employees expect every component to be paid simultaneously. Understanding the difference between salary, benefits, reimbursements, deductions, statutory payments, and documentation can make the process much clearer.
⏰ One common question is why the full settlement has not arrived even though employment has ended. The answer may depend on which component is pending and the rules applicable to that payment.
📋 Employees may wonder why the final amount differs from their monthly salary. Partial-month salary, leave, deductions, taxes, reimbursements, and notice adjustments can all change the final figure.
💼 Another common issue is an unexpected notice-period deduction. Employees should compare the deduction with their employment agreement and any written notice-waiver arrangement.
🧾 Missing reimbursement payments can create confusion after departure. Employees should check whether the claim was approved and whether the required supporting documents were submitted.
🏦 A PF balance should not automatically be expected as part of the employer’s final bank transfer. PF processing follows its own statutory account and claim mechanisms.
🎓 Gratuity can also require separate consideration. Eligibility and calculation depend on the applicable law and the employee’s qualifying circumstances.
🔍 Employees sometimes focus only on the final bank credit and overlook the settlement statement. Reviewing both provides a much clearer picture of what was calculated and paid.
📬 If an employer has not provided a settlement document, an employee can request a written statement showing the major components. This creates a clearer record for both parties.
📅 Employees should record important dates, including resignation, acceptance, last working date, and payment date. These dates are useful when checking applicable timelines.
🛡️ A company policy may explain internal settlement procedures, but statutory requirements should also be considered where applicable. Internal processes should not be treated as the only source of rights.
🧮 A good FnF calculation should be understandable without requiring guesswork. Each major amount should have a recognizable description and calculation basis.
💬 Written communication is usually more useful than repeated informal calls. Employees can clearly state the outstanding component and attach the relevant supporting document.
📚 Older online articles may describe previous labour-law rules. For a 2026 settlement, employees should verify important legal points using current official sources.
🌐 Employment circumstances can differ between workers. The applicable law may depend on factors such as the type of employment, establishment, wage component, and reason for separation.
🧾 Employees should preserve the final settlement letter even after receiving payment. It can serve as evidence of the amount calculated and the components considered.
🤝 Employers can also benefit from a transparent FnF format. Clear calculations reduce repeated questions and create a consistent record for payroll and HR.
💡 Employees should distinguish between an actual payment delay and a separate processing timeline. A statutory wage requirement may not necessarily govern every benefit or reimbursement.
⚖️ Where a substantial dispute remains, the appropriate legal or labour authority depends on the specific facts and applicable jurisdiction. Professional advice may be useful for complex cases.
🌿 The best practical approach is to keep a complete exit file. Salary slips, leave records, employment terms, tax documents, settlement statements, and payment proof can answer many future questions.
🌟 A carefully reviewed FnF settlement gives both sides a clear financial record after employment ends. Understanding each component helps employees move forward without confusing salary, benefits, deductions, and separate statutory processes.
FAQs
What is Full and Final FnF Settlement in India?
FnF settlement clears an employee’s financial dues after leaving a job.
How is Full and Final FnF Settlement in India calculated?
It includes salary, leave encashment, benefits, reimbursements, and deductions.
What is the 2-day rule for Full and Final FnF Settlement in India?
It refers to wage payment timing in certain employment-separation situations.
Does Full and Final FnF Settlement in India include leave encashment?
Yes, eligible unused leave may be included in the settlement.
Is gratuity part of Full and Final FnF Settlement in India?
Yes, gratuity may be included when statutory eligibility requirements are met.
Can notice period recovery reduce Full and Final FnF Settlement in India?
Yes, applicable notice recovery can reduce the final settlement amount.
What documents are needed for Full and Final FnF Settlement in India?
Salary slips, employment documents, leave records, and clearance records are commonly used.
Can employees check Full and Final FnF Settlement in India themselves?
Yes, employees can compare the settlement with their employment and payment records.
Does Full and Final FnF Settlement in India include PF?
PF generally follows a separate statutory withdrawal or transfer process.
What should an employee do if Full and Final FnF Settlement in India is incorrect?
Ask HR for a detailed calculation and raise any discrepancies with supporting records.
Conclusion
A clear understanding of Full and Final FnF Settlement in India helps employees review salary, leave, deductions, reimbursements, notice adjustments, and statutory benefits with greater confidence. The settlement should be checked against reliable employment and payroll records rather than judged only by the final bank credit.
In 2026, Full and Final FnF Settlement in India should also be understood alongside the applicable labour-law framework and the distinction between wages and other settlement components. Keeping the settlement letter, final payslip, payment proof, tax records, and statutory-benefit information can provide a useful long-term employment record.
Read More What Does PMO Mean in Text? Meaning, Slang, Uses & Examples (2026)